

Hi Partner 👋
One of my favorite books? The Outsiders by William Thorndike.
He analyzes the best CEOs in the world and what makes them unique.
Let’s learn how you can find and invest in the best CEOs in the world.
The Outsiders
In the past, we have already made a summary of Will Thorndike’s book.
In case you missed it, you can grab it here:
![Book Notes] The Outsiders: Eight Unconventional CEOs and Their Radically Rational Blueprint for Success | by Kyle Eschenroeder | Medium](https://substackcdn.com/image/fetch/$s_!mRRb!,f_auto,q_auto:good,fl_progressive:steep/https%3A%2F%2Fsubstack-post-media.s3.amazonaws.com%2Fpublic%2Fimages%2F26b18067-7801-4e72-8bf9-02294a1e920d_1200x848.png "Book Notes] The Outsiders: Eight Unconventional CEOs and Their Radically Rational Blueprint for Success | by Kyle Eschenroeder | Medium")
Forget Wall Street CEOs
How do you think the best CEOs on Earth look?
When you ask someone on the streets, they’ll probably answer the following:
He flies private or at least business class
He has a fancy Wall Street office
He has years of experience
He has a lot of charisma
The ultimate businessman in a picture:
The ultimate business leader, right?
Think again.
The best CEO could be your neighbor.
He’s a true family person, happily married, and living a balanced life.
Great CEOs keep things simple. They value every dollar and prefer jeans and T-shirts over designer suits.
They don’t need luxury to prove their worth. They show their greatness by creating long-term value for shareholders.
Mark Leonard of Constellation Software is a great example of this.
By the way, have you heard of Pinetree Capital (TSE: PNP)?
It’s a publicly traded fund focused on VMS businesses.
They benefit from the knowledge and experience of Constellation Software.
It’s run by Damien Leonard, Mark Leonard’s son.
Does Damien have the same iconic beard as his dad? Who knows, he avoids the media just like his father.
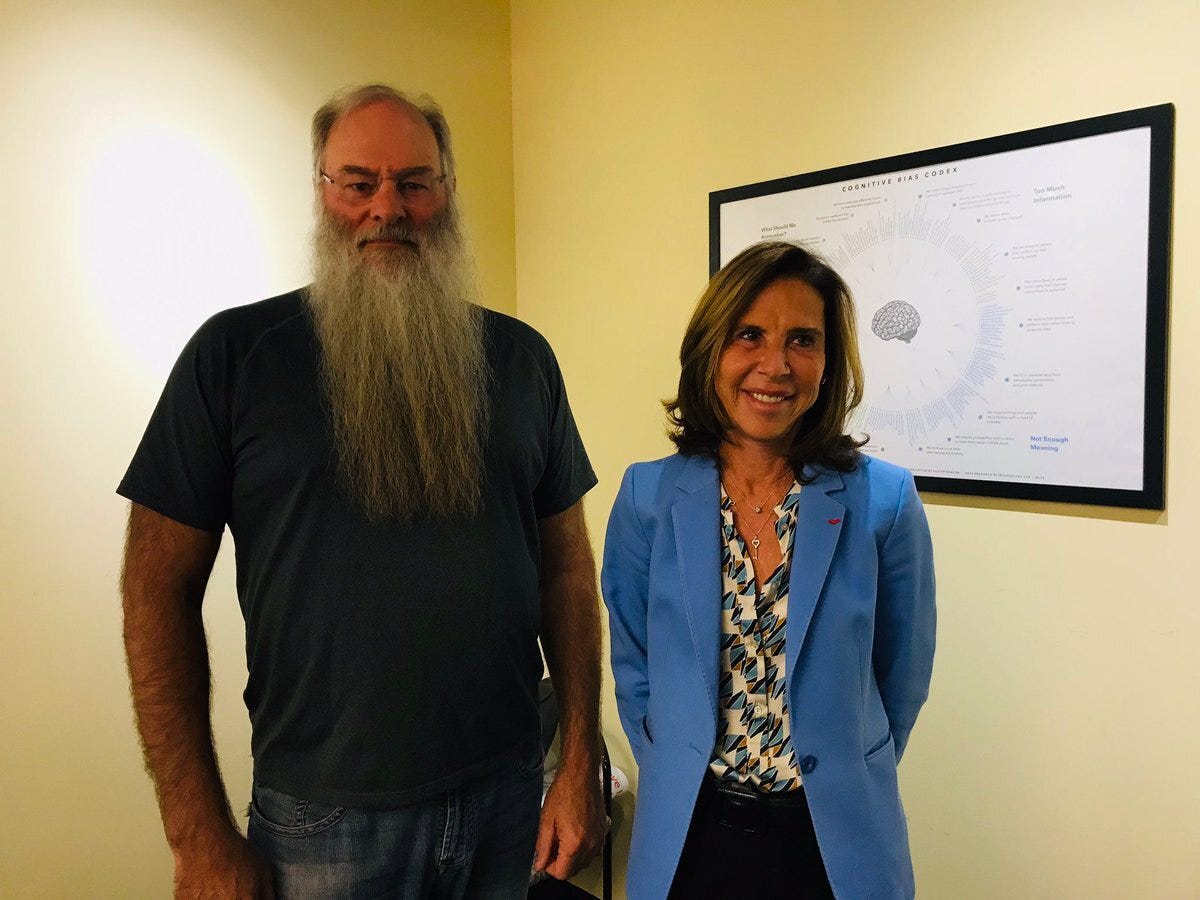
Great CEOs stay outside the spotlight and work in Spartan offices.
Interestingly, there’s an inverse relation between the construction of elaborate new headquarters and investor returns.
The simpler the office, the higher the return for shareholders.
Just look at Warren Buffett’s modest office.
A fun fact? He still works at his father’s desk from the 1950s.
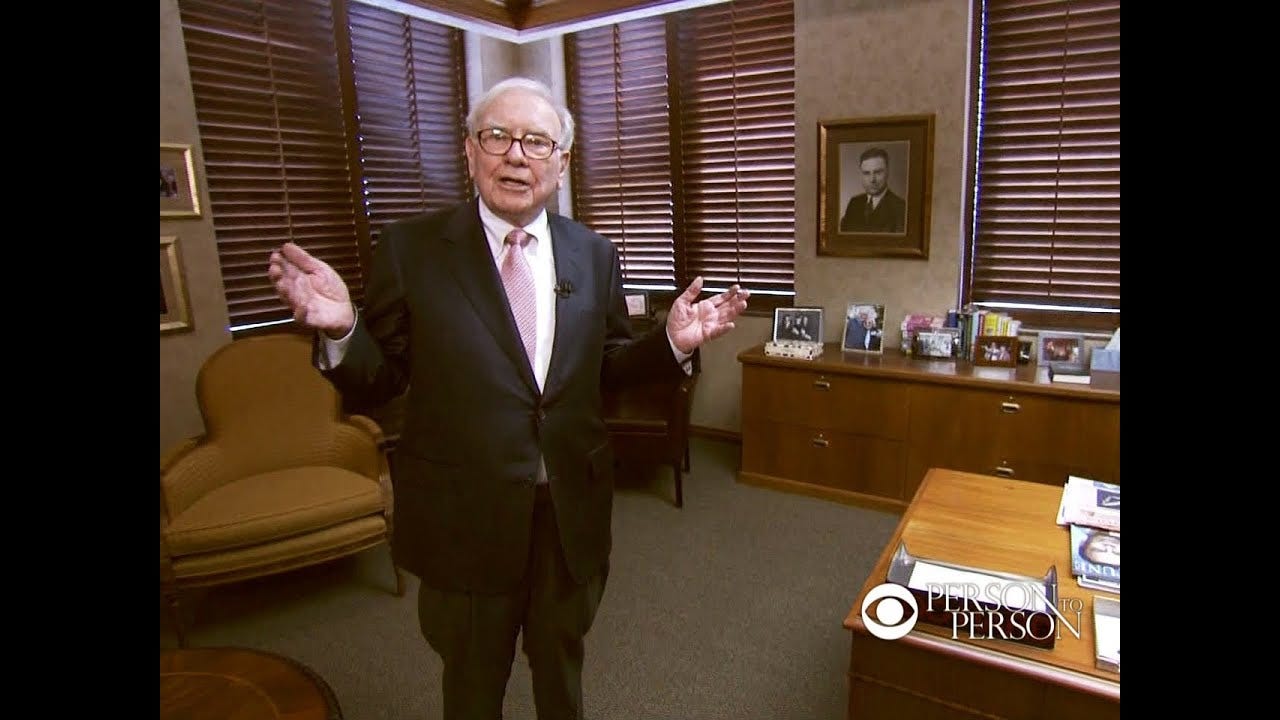
And these basic offices? They are often in small towns far away from Wall Street’s noise.
This gives these managers a big advantage: it helps them to avoid herd behavior.
As Buffett said:
“I have been surprised time and again by how institutions resist change and pursue actions that make no sense, simply because they are following the crowd.” - Warren Buffett

In other words, the best managers are independent thinkers.
“It’s impossible to produce superior performance unless you do something different from the majority.” - John Templeton
Here’ the difference between an ‘Outsider’ CEO and a ‘normal’ CEO:

Outsider CEOs are known as excellent capital allocators.
Capital allocation
The most important task of management is capital allocation.
Mark Leonard, one of the best CEOs ever, said the following about this topic:
“Over the long term, stock returns will be determined by the capital allocation decisions of the CEO. Two companies with identical operating results and different approaches to allocating capital will derive two very different long-term outcomes for shareholders.”
In other words, a single capital allocation decision can change everything.
A great CEO isn’t just an operator, they’re an investor.
That’s exactly why Warren Buffett once said:
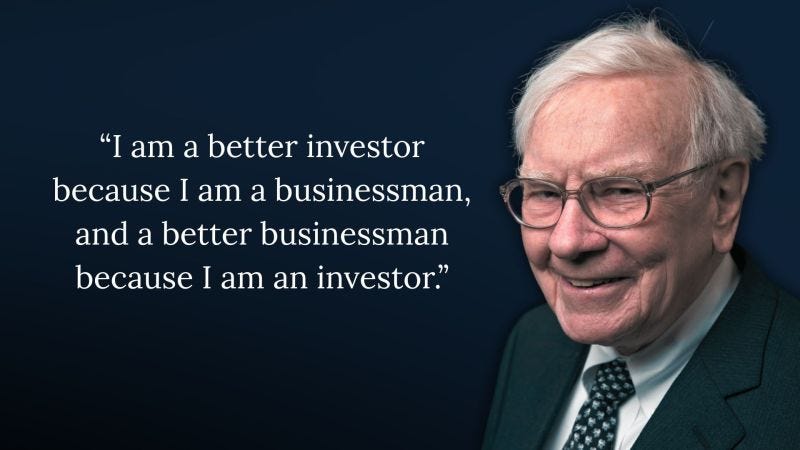
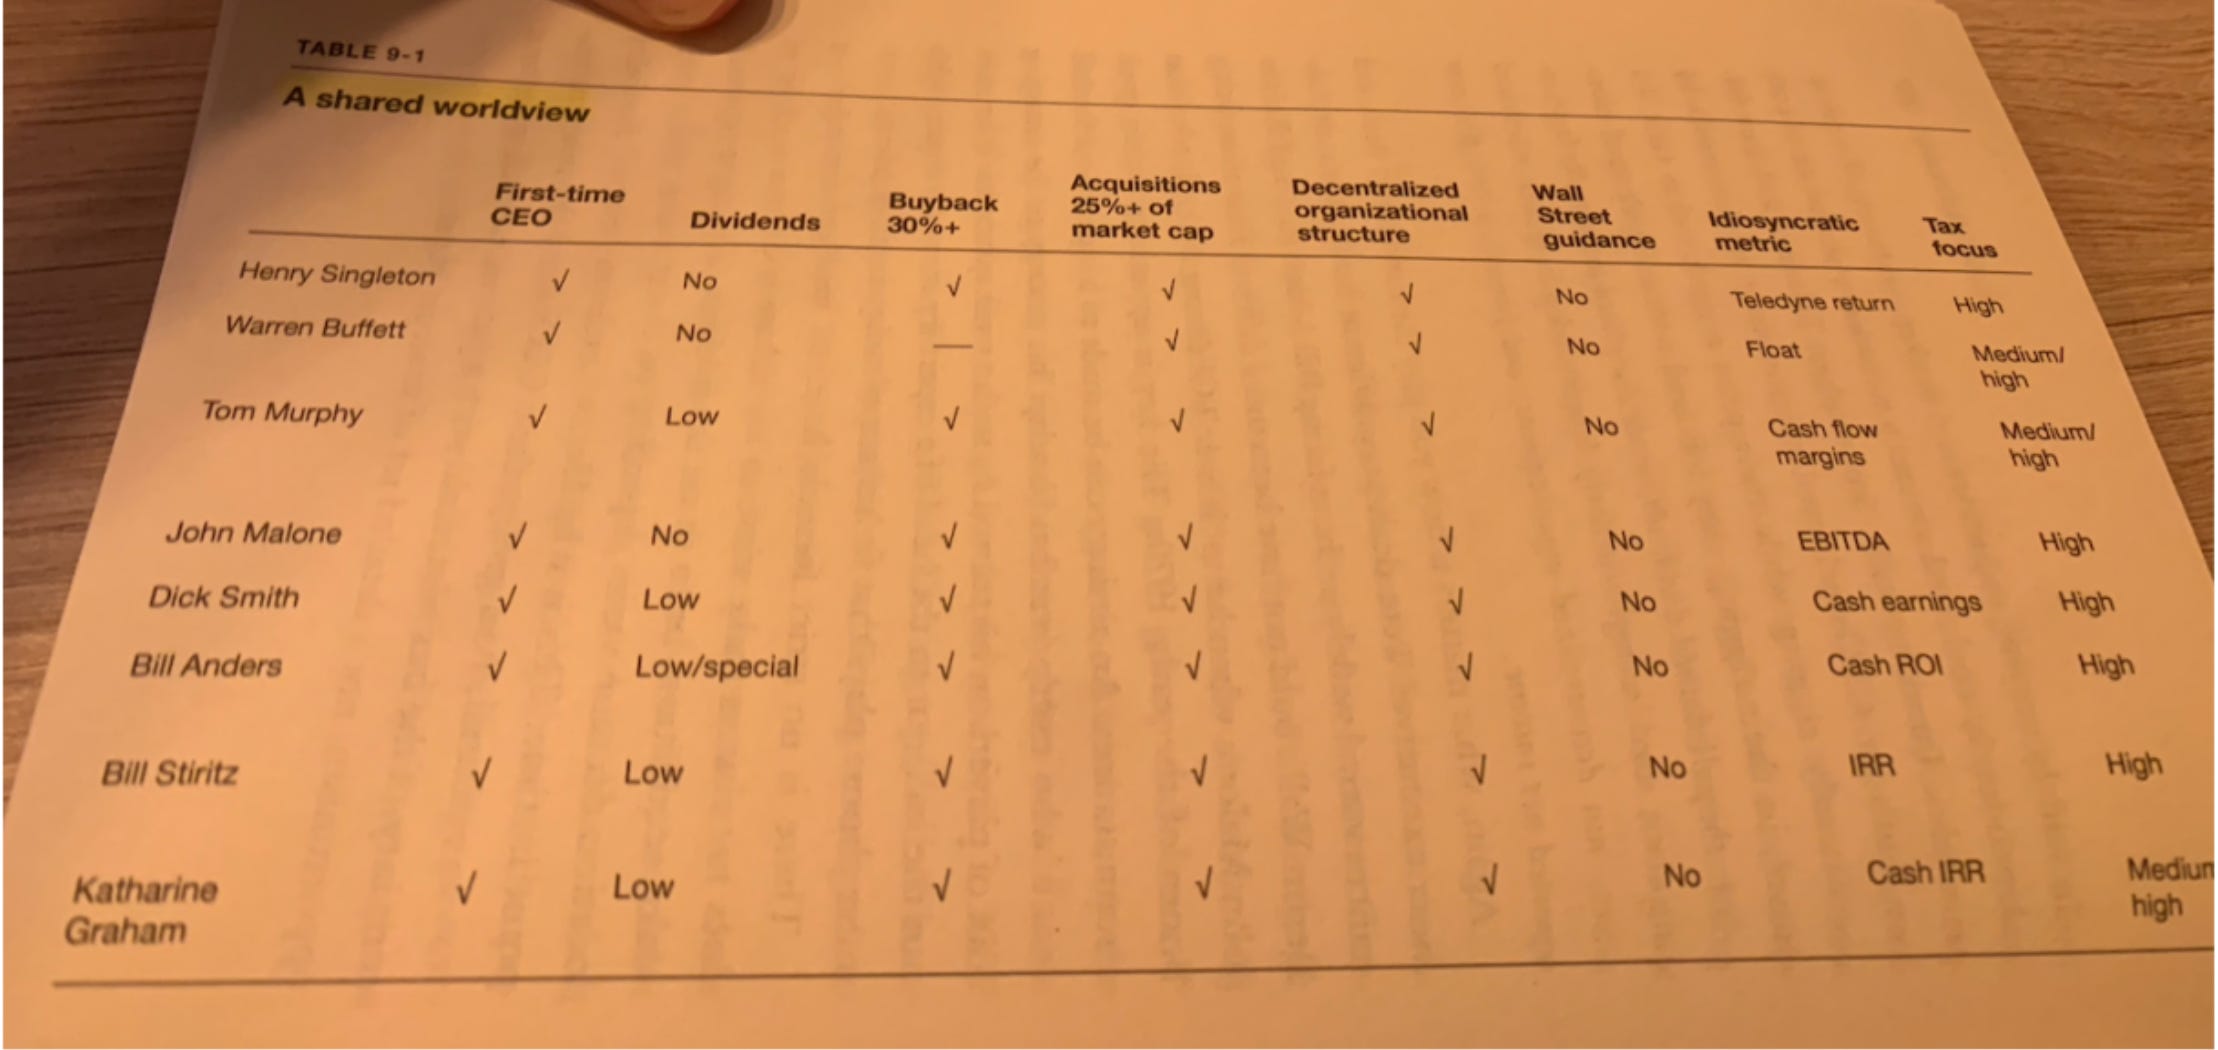
Another thing great CEOs have in common? They don’t like to pay dividends.
They prefer acquisitions and share buybacks instead.
Many CEOs mentioned in The Outsiders heavily bought back their shares when their stock price crashed.
“Sometimes the best investment is your own stock” - William Thorndike
Our Outsider CEO
Let’s put the theory to the test.
Our Portfolio has a CEO who fully embodies the Outsider principles.
That CEO? August Troendle (CEO & Founder of Medpace).
If you want to check yourself if a CEO meets Outsider standards, look at two things:
Capital Allocation
Track Record
Let’s see how August is doing.
Capital Allocation
Imagine you have $10,000 in savings and want to entrust it to an investor.
How would you judge their performance?
It’s simple: you’d check whether they turned every dollar you invested into more dollars.
Managers are investors, too. You should evaluate them the same way.
Warren Buffett captured this idea with his famous $1 Test.
“We test the wisdom of retaining earnings by assessing whether retention, over time, delivers shareholders at least $1 of market value for each $1 retained.” Warren Buffett’s 1983 shareholder letter
In other words, companies should create more than $1 in value for every $1 they keep.
An example:
If a company earns $100 million and creates only $50 million in shareholder value, it fails.
If it earns $100 million and creates $150 million in value, it passes.
Now, let’s look at the situation for Medpace.
Here’s the evolution of Medpace’s Net Income.
It went from $39.1 million to $491.5 million.
That’s an increase of $452.4 million.
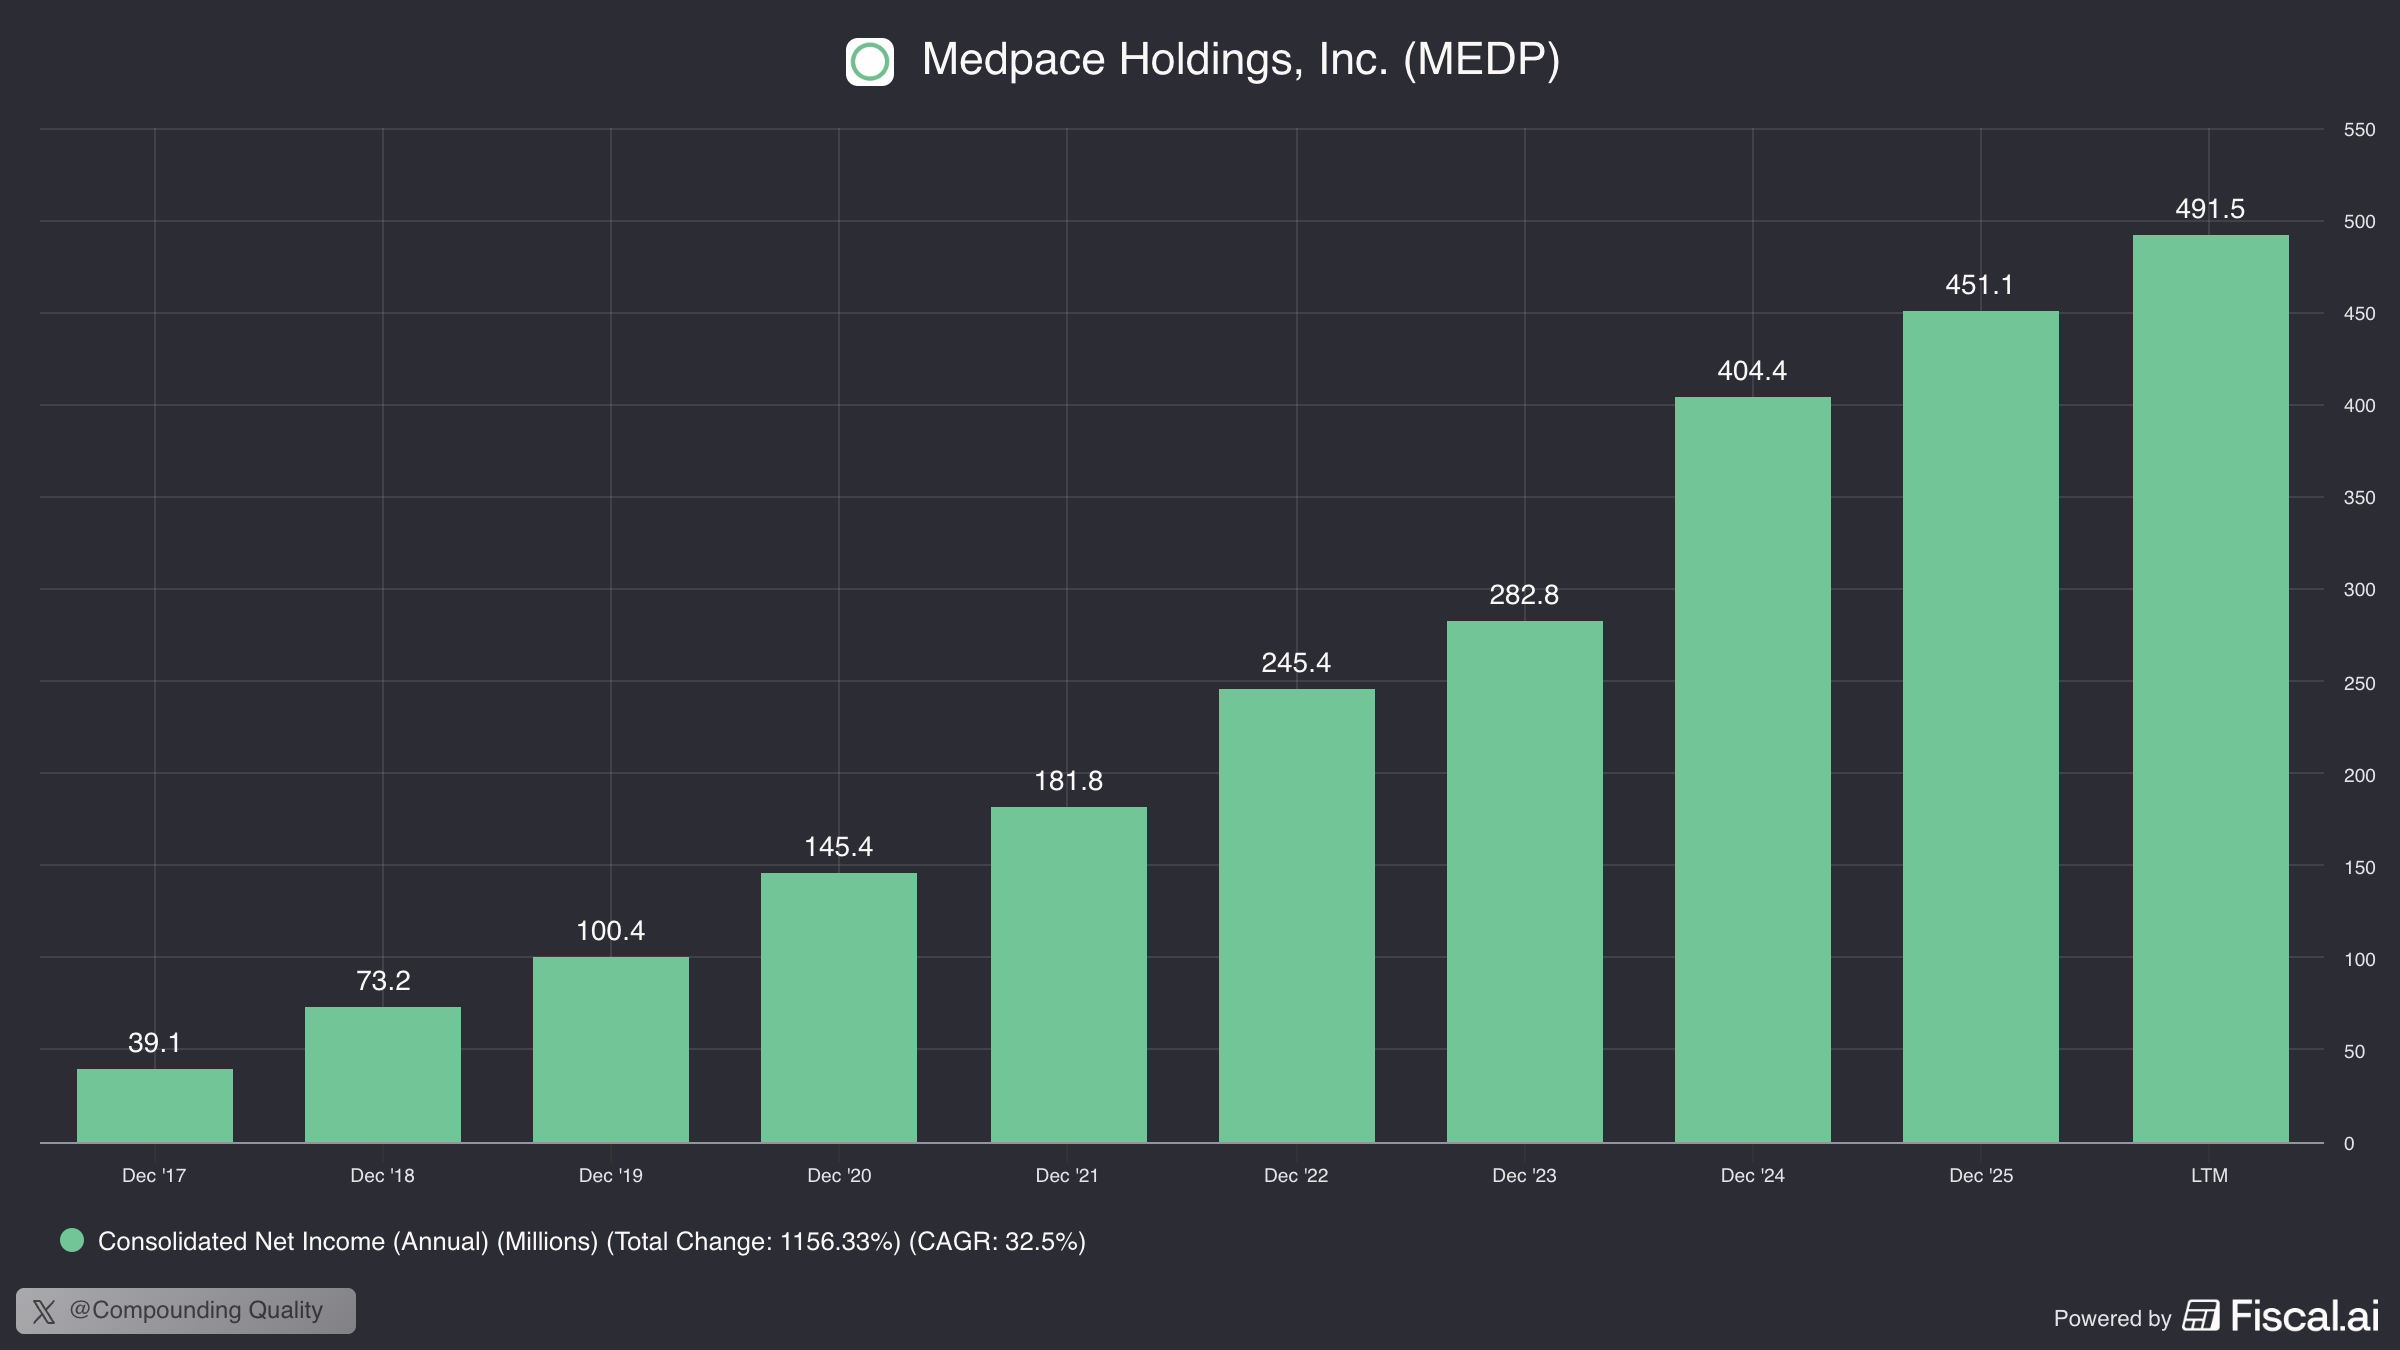
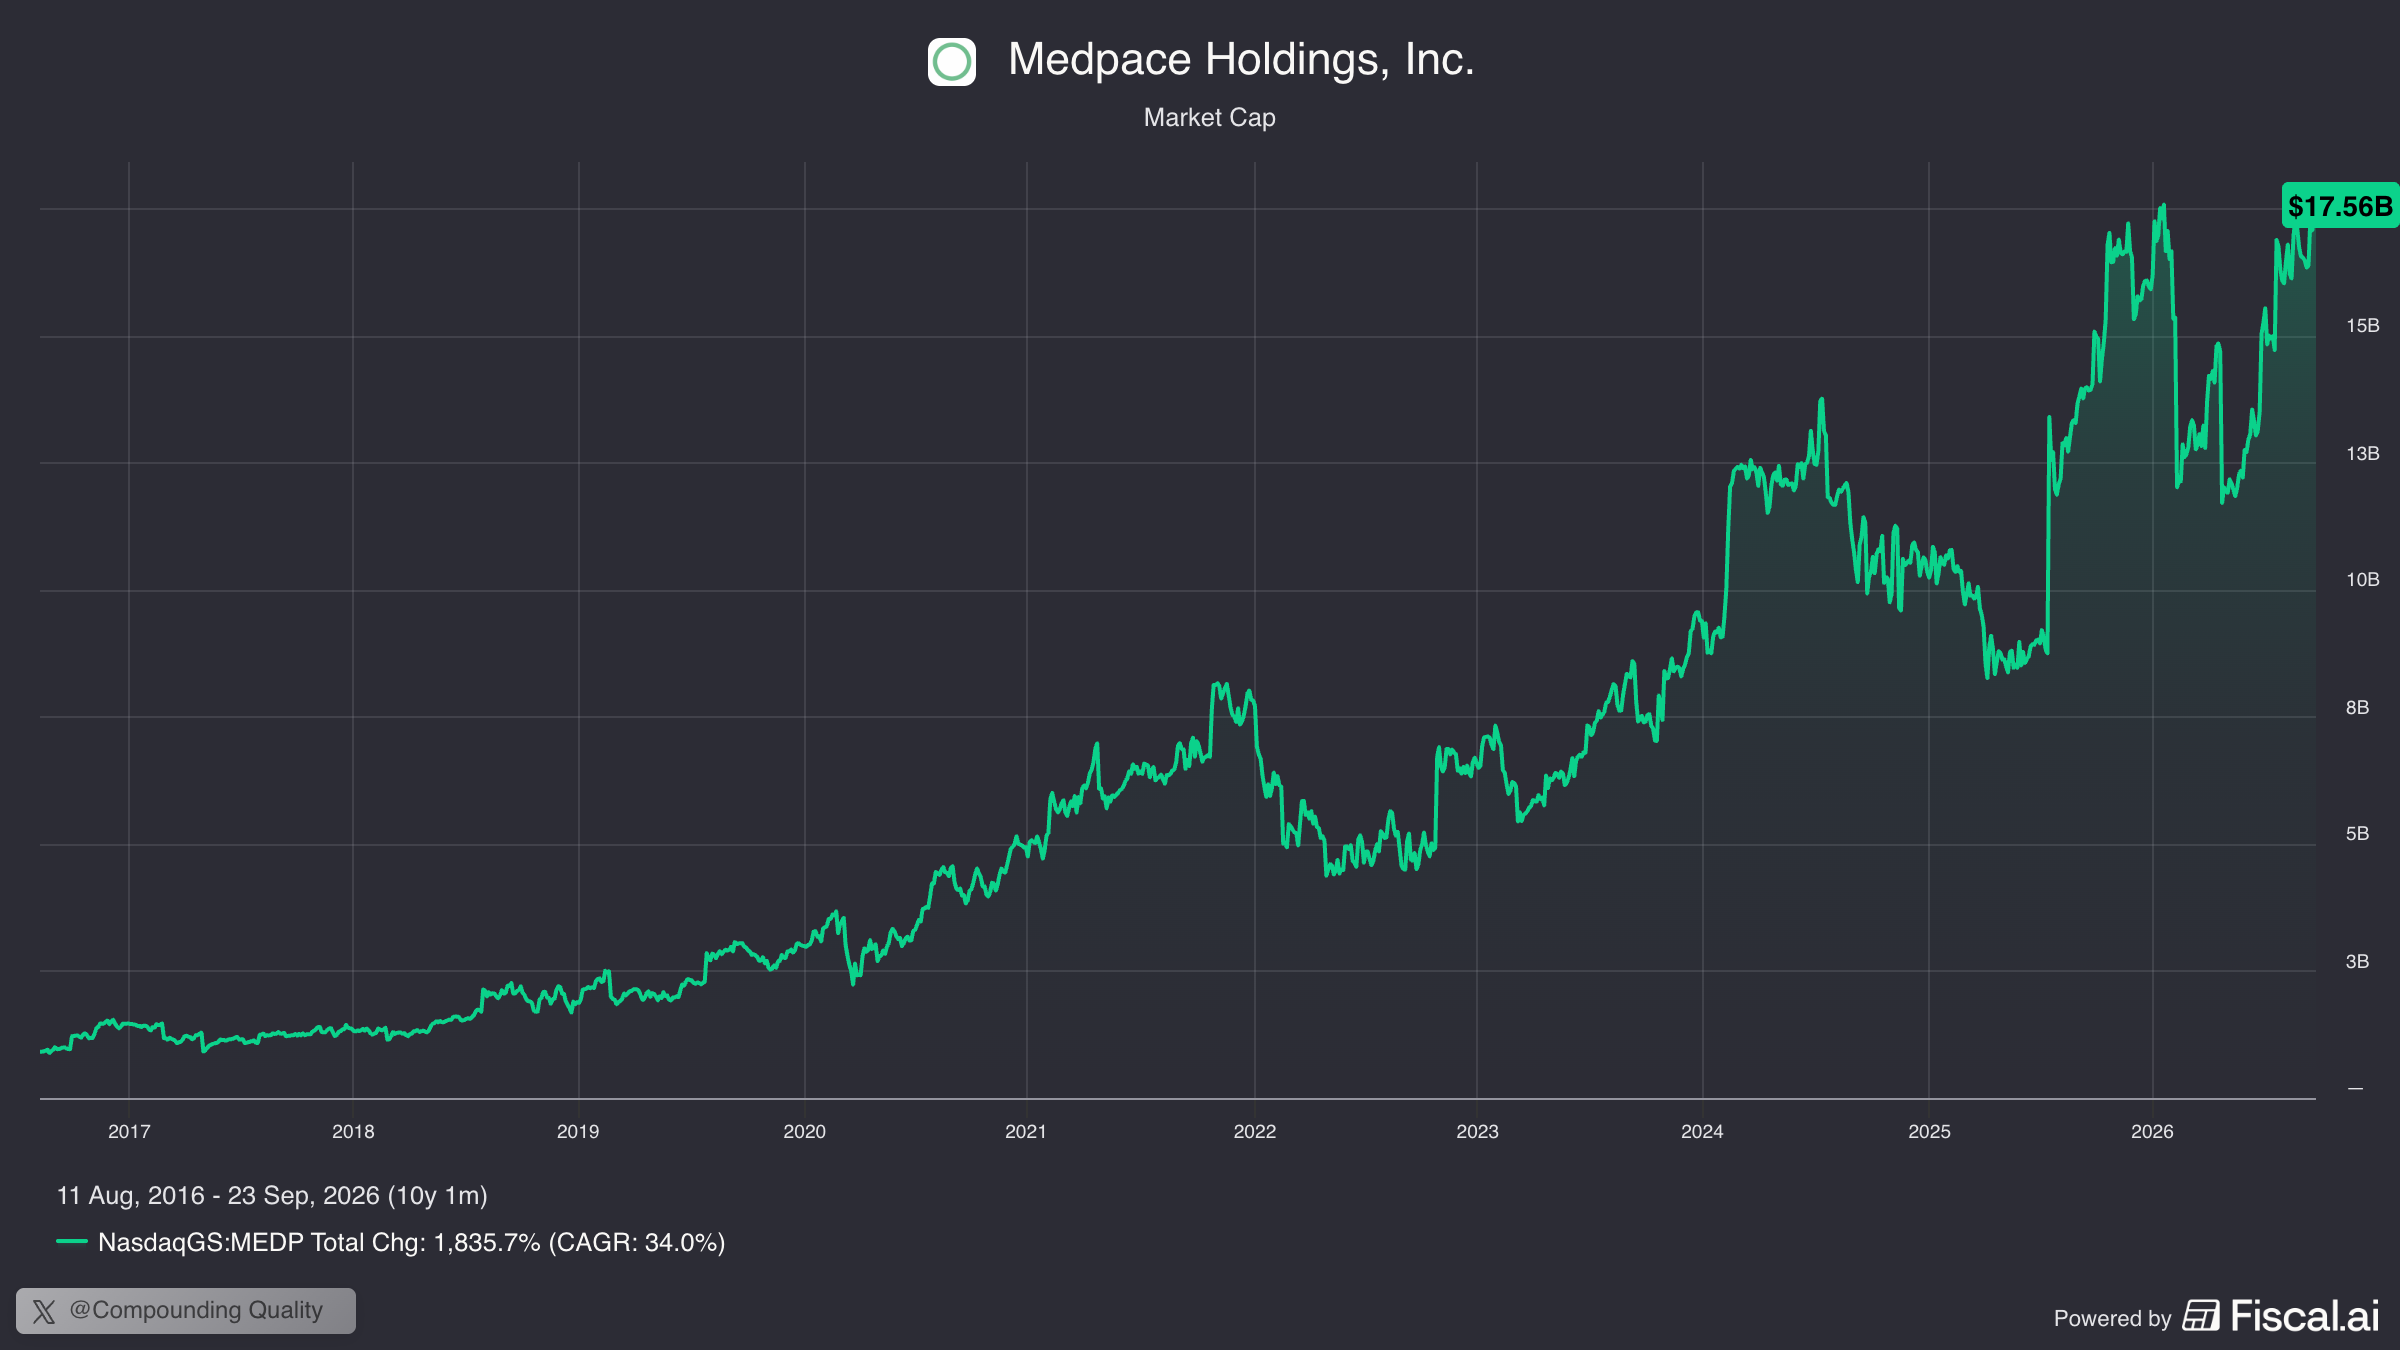
Since 2017, Medpace’s Market Value went up from $1.4 billion to $17.5 billion.
That’s an increase of $16.1 billion
This means August Troendle can be seen as an excellent capital allocator.
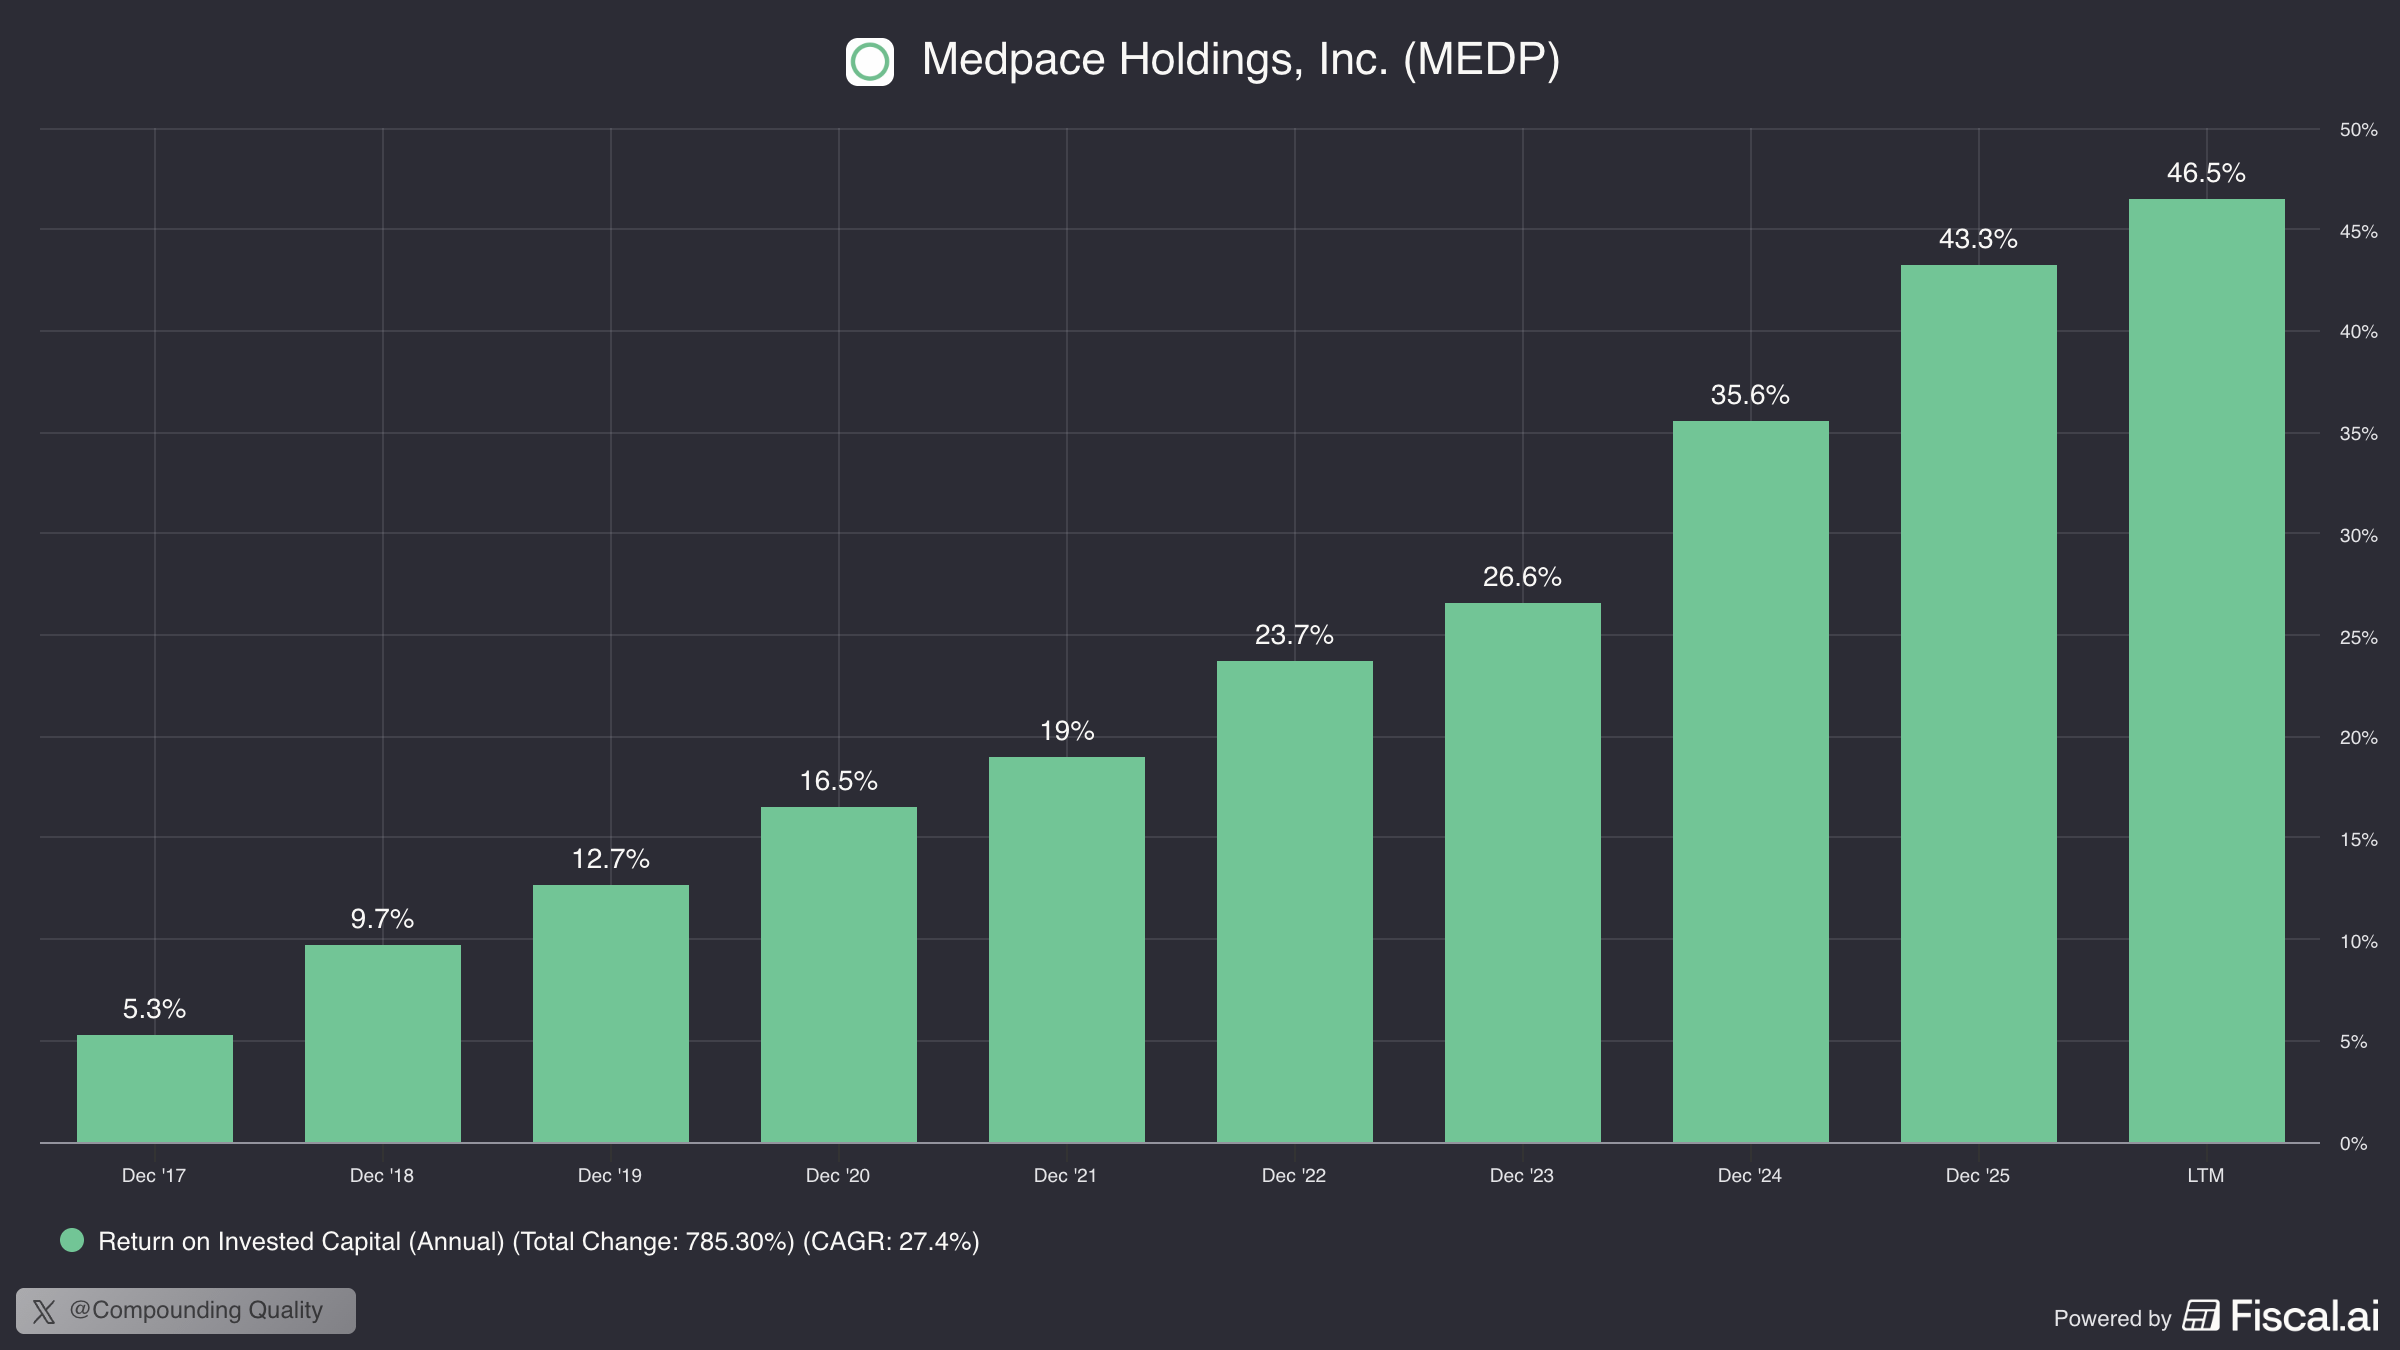
Another way to evaluate management’s capital allocation skills is to examine the evolution of Return on Invested Capital (ROIC).
As a rule of thumb, I want ROIC to be consistently above 15.0%.
Here’s what this number looks like for Medpace:
Track record
The track record of management can already tell you a lot.
When a CEO has been leading the company for 20 years and the business has done exceptionally well over this period, it tells you something.
Let’s see how Medpace has performed.
We begin with the returns to shareholders.
Since the IPO in 2016, the share price has grown at a CAGR of 34.0%.
These are very attractive returns.
Conclusion
That’s it for today.
We want to invest in companies led by excellent managers.
The best book to learn about excellent managers? The Outsiders by William Thorndike.
Use this checklist to find the best leaders:
Capital Allocation:
The $1 Test of Warren Buffett
The evolution of the company’s ROIC
Track Record:
How shares have performed under the manager
Growth of Owner’s Earnings
It’s great to see August Troendle (CEO of Medpace) ticks all the boxes.
Everything In Life Compounds
Pieter
Used sources
Interactive Brokers: Portfolio data and executing all transactions
Finchat: Financial data
Plain offices and avoiding herd behavior line up with how I judge managers.
Yes, that is exactly how it works, and smart investors know why.
Independent thinking is indispensable, especially for long-term "quality compounding" investors, because above-average returns are not generated by imitating the majority, but by forming one’s own judgment regarding business quality, capital allocation, and the price actually paid.
The crucial benchmark is not how much earnings or market capitalization have grown, but rather whether management can consistently transform retained earnings into additional intrinsic value per share.
Achieving high incremental returns on capital while avoiding dilution, overpriced acquisitions, and vanity-driven, ill-advised investments.
Thinking outside conventional patterns is precisely what helps one distinguish between an outstanding company and an outstanding stock!
Even an excellent CEO can lead to a disappointing investment if the valuation is excessive.
Conversely, an unassuming capital allocator can deliver exceptional results through disciplined reinvestment and patient compounding.
Long $MEDP 💸🕵️♂️
Ultimately, the "one-dollar test" applies to investors themselves, too!
Anyone aiming to create more than one dollar of intrinsic value for every dollar invested must first have the courage to think differently from the herd.
Because the stock market does not reward the most original opinion, but rather the one that proves its worth over the long term through real growth in value per share.